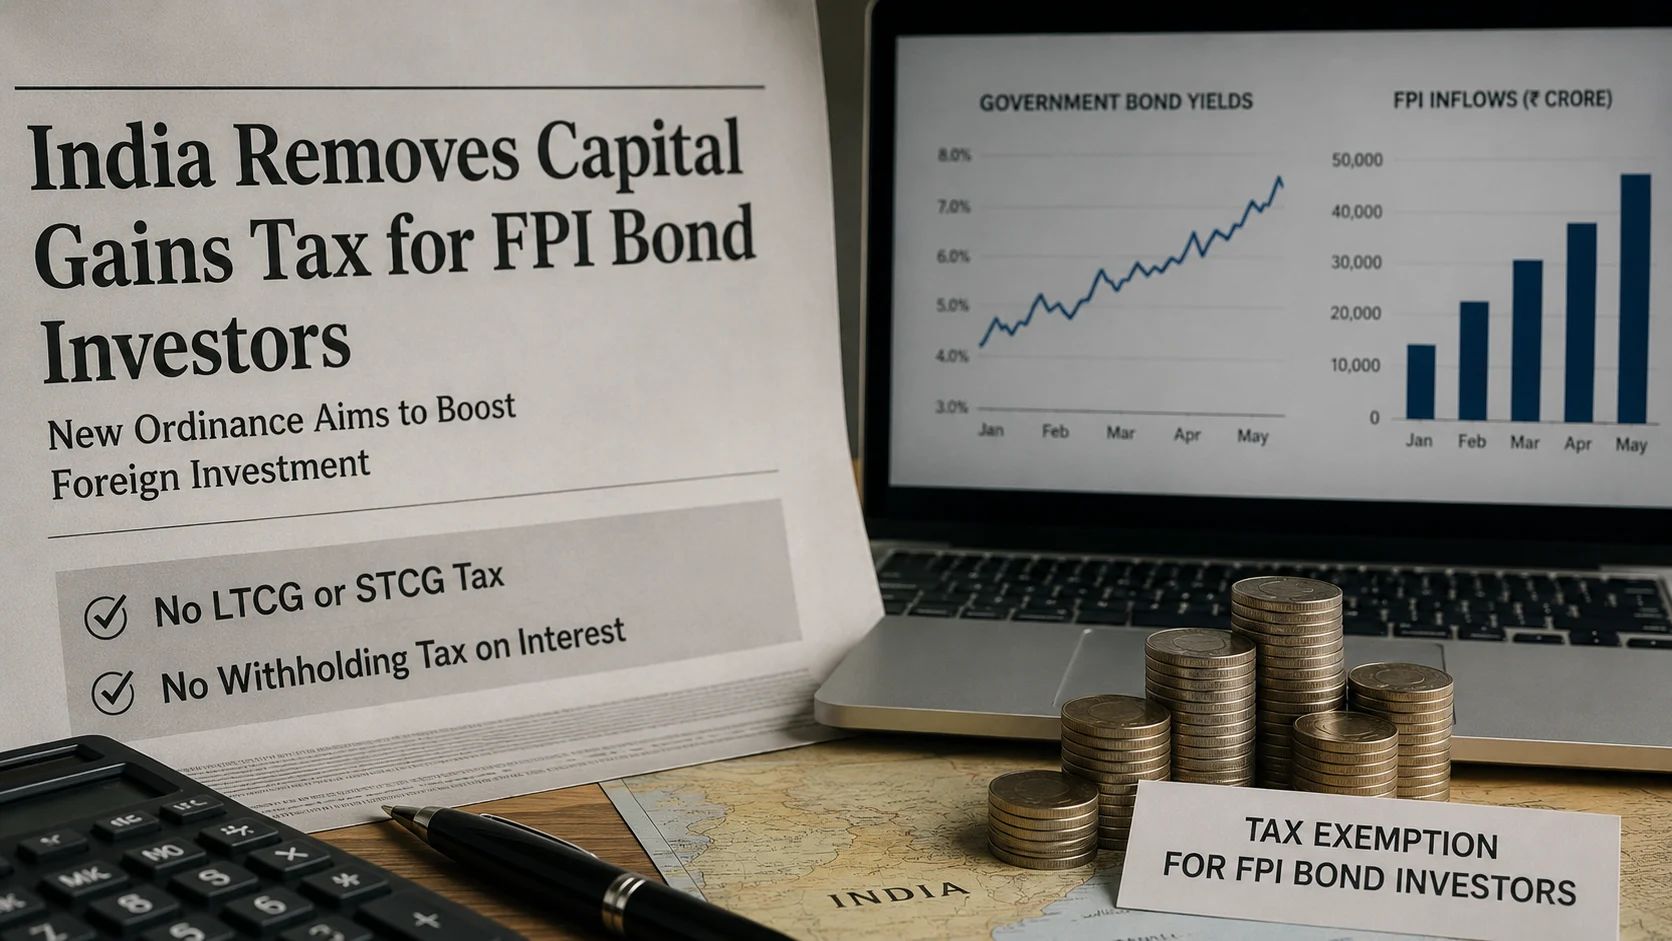
In an aggressive push to cement its position across global sovereign debt benchmarks, the Indian government enacted a decisive amendment to the Income Tax Act via presidential ordinance, fundamentally rewriting the fiscal terms under which foreign capital enters the domestic government securities (G-Sec) market.
The Income-tax (Amendment) Ordinance of June 2026 eliminated long-term capital gains tax (LTCG) and short-term capital gains tax (STCG) for eligible Foreign Portfolio Investors (FPIs) on central government securities, while simultaneously removing the withholding tax on coupon income. New Delhi has turned Indian sovereign paper into one of the most tax-efficient sovereign bond instruments across emerging Asia.
This reform is significant. The Union Cabinet wiped out capital gains tax liability for FPIs holding central government securities and removed the withholding tax on interest income. Because this is retroactive to April 1, 2026, Indian sovereign bonds have suddenly become highly competitive for global fixed-income allocators. However, the sheer speed of this move is striking: ordinances bypass the standard Union Budget process, which normally requires a published Revenue Foregone Statement alongside any significant tax change. The government announced no official estimate of what this exemption costs the treasury annually. That institutional gap is the core accountability concern this article examines.
From a market perspective, the rationale is clear. This eliminates the "index drag" that occurs when domestic yields don't match the gross yield calculations used in JPMorgan and Bloomberg indices. It also supports the Rupee by attracting dedicated debt capital inflows that partially offset the currency pressure from equity outflows. For foreign investors, the net return improvement is immediate and substantial — removing taxes that previously reduced their effective yield significantly.
But there is a fiscal trade-off the government has not publicly quantified. The ordinance route meant no floor debate in Parliament before implementation. The government is essentially providing a tax subsidy to large foreign institutional funds while domestic retail investors buying the same government bonds continue to pay full income tax on interest income. The scale of this implicit subsidy remains unestimated in any official document.
How the June 2026 Ordinance Changed the Market
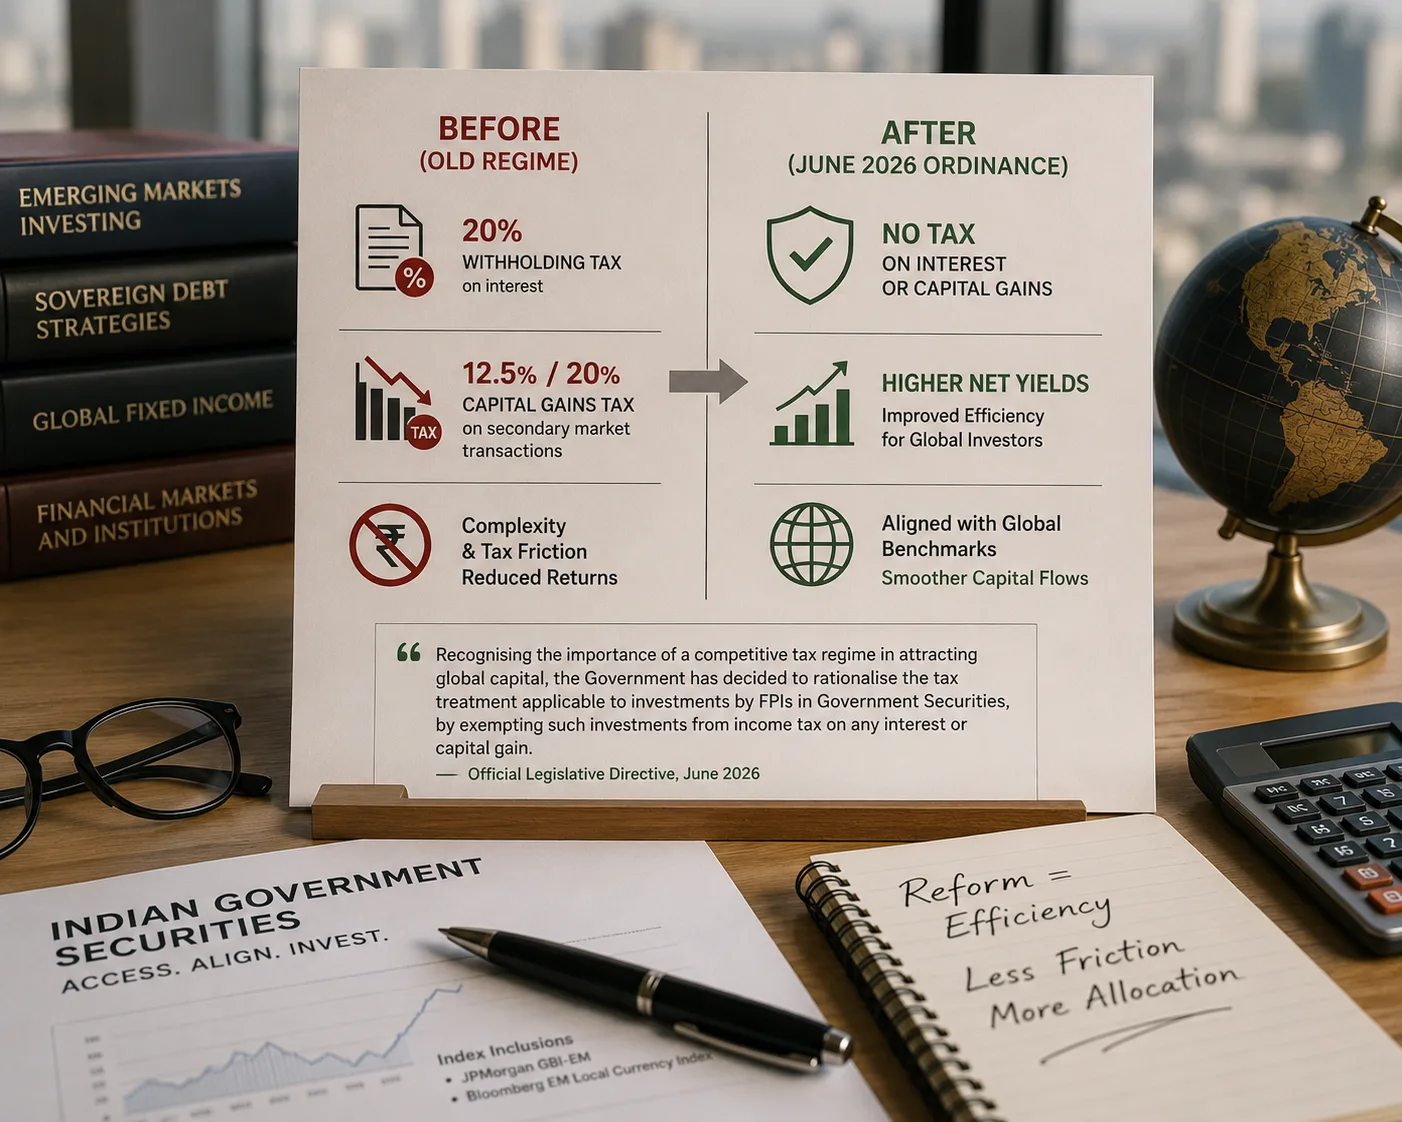
The new June 2026 framework fundamentally changed how foreign sovereign bond investing works in India. Under the pre-ordinance regime, offshore managers accessing the Indian debt market faced a layered tax structure. Semi-annual interest payments on Fully Accessible Route (FAR) securities were subject to withholding tax at the source. Short-term and long-term capital gains taxes applied on secondary market transactions, with rates varying by investor category and applicable tax treaty. For managers without bilateral treaty coverage, the rates were particularly penalizing.
The 2026 Ordinance removed these layers entirely for eligible FPIs. Institutional systems that model gross yields can now treat them as net yields without adjusting for withholding or gains tax. This is a material change for passive fund managers running benchmark-tracking mandates, where even small tax-driven tracking errors create meaningful underperformance relative to index.
This matters because of how global index inclusion mechanics work. When a country's bonds are added to indices like JPMorgan's GBI-EM or Bloomberg's EM Local Currency Index, passive capital allocation follows automatically. But passive funds operate on the assumption of zero tax friction in yield calculations. Before this reform, India's withholding tax structure was causing persistent tracking errors, giving passive managers a built-in incentive to underweight Indian paper. The 2026 reform corrects this misalignment.
"Recognising the importance of a competitive tax regime in attracting global capital, the Government has decided to rationalise the tax treatment applicable to investments by FPIs in Government Securities, by exempting such investments from income tax on any interest or capital gain." — Ministry of Finance, June 2026
The Hidden Cost: A Subsidy Without a Published Price Tag
The absence of a published cost estimate is the core transparency problem. In standard Budget practice, significant tax changes come with a Revenue Foregone Statement — a line-item disclosure of what the government is giving up. Because the June 2026 change was implemented through a Cabinet Ordinance rather than the Finance Act, no such statement was published alongside it.
An important procedural note: Under Article 123 of the Constitution, ordinances must be laid before Parliament when it reassembles, and they lapse six weeks after that unless ratified. This means parliamentary oversight exists — but it comes after the fact, not before. The accountability gap is not that Parliament can never review this change, but that the normal pre-Budget consultative process (which produces published revenue estimates) was bypassed entirely.
To assess the fiscal scale, we can construct a rough estimate from public data. According to RBI data, Foreign Portfolio Investors hold approximately ₹3,80,487 crore in Indian sovereign debt — approximately 3.38% of the total ₹112.42 lakh crore in outstanding central government securities. The pre-ordinance tax structure varied by investor category, transaction type, and applicable treaty, making a precise revenue foregone calculation complex. On the withholding tax side alone — where a blanket rate applied to all coupon payments — the annual revenue foregone can be estimated in rough order-of-magnitude terms:
| Tax Component | Pre-Ordinance Treatment | Post-Ordinance | Rough Order of Magnitude — Annual Revenue Foregone |
|---|---|---|---|
| Withholding Tax on Interest Income | Applicable rate (varied by treaty; up to 20% for non-treaty FPIs) | 0% | ₹4,000 – ₹5,000 crore |
| Long-Term Capital Gains Tax (12+ months) | 12.5% per Finance Act 2024 | 0% | ₹500 – ₹800 crore |
| Short-Term Capital Gains Tax | Varied by investor category and applicable provision | 0% | ₹200 – ₹400 crore |
| Total Estimated Fiscal Subsidy | ₹4,700 – ₹6,200 crore annually (rough estimate) |
Advertisement
These are rough estimates derived from FPI holdings data and pre-ordinance statutory rates. Actual revenue foregone depends on treaty coverage, FPI category mix, portfolio turnover, and realized gains — data the government has not disclosed. A proper Revenue Foregone Statement would require official actuarial calculations.
The immediate market response validated the policy's intent: FPI inflows into FAR bonds of over ₹16,567 crore were recorded in a short window after the announcement. But attracting that capital came at an unquantified cost to the public exchequer.
The Mechanics of the Index Fund Effect
To understand why the government moved this quickly, you need to understand how global index tracking works. Most modern institutional fixed-income investment follows passive mandates that rely on automated rebalancing against published benchmarks. When India's bonds are included in the JPMorgan GBI-EM and Bloomberg EM indices, billions in non-discretionary purchases follow — but only if the tax friction is minimal enough that gross yield calculations align with actual investor returns.
By early 2026, the conditions for maintaining those index-driven inflows were deteriorating. Foreign institutional investors had been selling domestic equities at a significant pace — over ₹2.5 lakh crore in net outflows — putting sustained pressure on the Rupee. As the currency weakened, the effective net return on Indian bonds for unhedged foreign investors was declining even faster than yield data suggested. Keeping the withholding tax at its prior level would have made Indian bonds materially less competitive against Brazilian, Indonesian, and South African sovereign paper in the same global benchmark.
By eliminating withholding taxes and capital gains taxes, the government effectively set the tax variable in the net-yield equation to zero. A 6.9% gross yield became a 6.9% net return for eligible FPIs. This was a calculated adjustment designed to offset the Rupee's depreciation pressure using the tax code rather than burning foreign exchange reserves. The trade-off: revenue foregone vs. currency stability and index inclusion maintained.
"The 2026 Ordinance represents a deliberate transfer of fiscal revenue to international capital pools in exchange for local currency debt stability — a trade-off the government has not yet explained publicly in quantitative terms."
Structural Disparities and the Accountability Gap
There is a genuine fairness tension in this policy. A domestic retail investor holding the same FAR bond as an offshore institutional fund pays income tax at their applicable slab rate on coupon income. The offshore fund, after the 2026 ordinance, pays nothing. This is not a minor rate differential — it is a total exemption for one category and full tax liability for another, on identical assets.
The deeper issue is process transparency. When the government provides an explicit subsidy through expenditure, it appears in the Union Budget's Demands for Grants and is subject to CAG audit. The June 2026 tax exemption functions as an implicit subsidy — economically identical to collecting the tax and writing a refund cheque to FPIs — but it does not appear as a line item in any budget document. This does not place it beyond all oversight: the Comptroller and Auditor General's mandate extends to revenue relinquishment, and Parliament must ratify the ordinance. But it does mean the public never received a formal cost estimate before the policy took effect.
This creates a structural asymmetry in accountability. India successfully attracted ₹16,567 crore in FPI inflows quickly. But the annual ongoing cost of maintaining zero tax on FPI G-Sec income — running to potentially thousands of crores — has never been disclosed. Whether that trade-off is worth it is a legitimate policy debate. It cannot be a debate the public participates in if the numbers are never published.
Read Further
- Government Issues Ordinance to Exempt FIIs from Capital Gains Tax on Government Securities — ANI, June 5, 2026
- FPI Investments in G-Secs Become Tax-Free Under Income-tax (Amendment) Ordinance, 2026 — Ministry of Finance Statement via CAClubIndia, June 2026
- Government Issues Ordinance Exempting Foreign Investments in G-Secs from Capital Gains Tax — India TV News, June 2026
Sources and methodology: This article draws on the Ministry of Finance press release on the Income-tax (Amendment) Ordinance (June 5, 2026), RBI data on FPI holdings in government securities, JPMorgan GBI-EM and Bloomberg index documentation, and the ANI, CAClubIndia, and India TV News reports cited above. Revenue foregone estimates are rough calculations based on FPI holdings and pre-ordinance statutory rates — not an official government assessment. Tax rate figures reflect the general statutory structure; actual rates for specific FPI categories depend on applicable bilateral tax treaties. Written by the OneMint editorial team. Last reviewed October 2026. For educational purposes only; does not constitute tax, investment, or legal advice.
Advertisement